


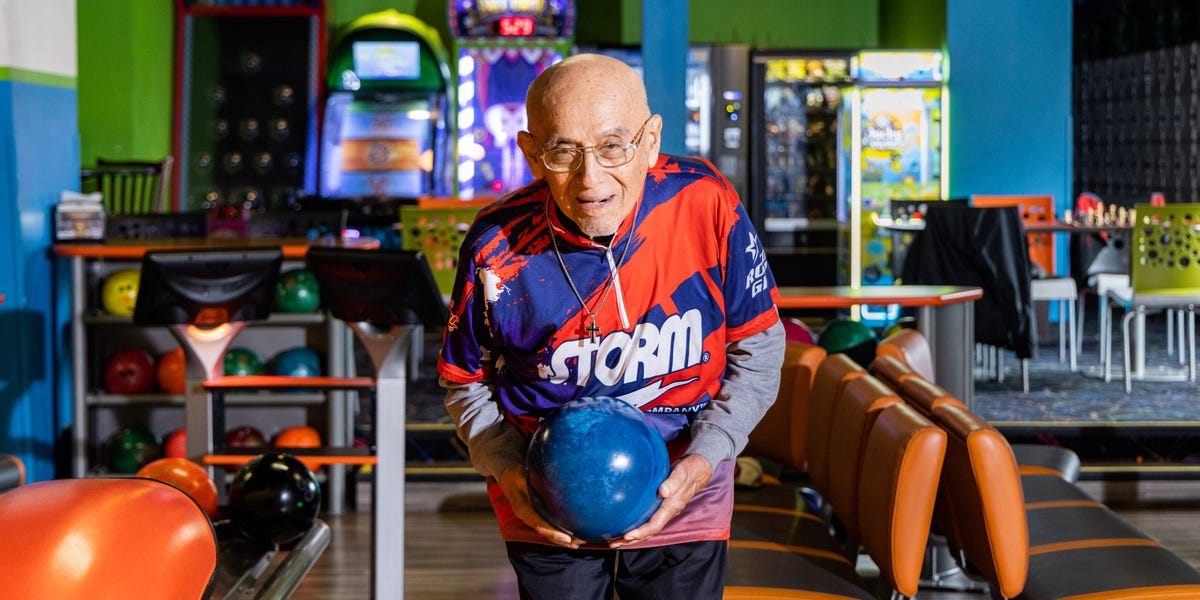
A Retirement Success Story Without Planning
Rich Colorado, at 65, stepped into retirement without any concrete financial plan. Avoiding stock investments, he opted to place his earnings in CDs yielding 4-5%, and his wealth grew effortlessly to over $1.3 million. Currently, he holds approximately $750,000 in liquid assets, with his residence valued at $600,000.
Originally hailing from El Salvador, Rich moved in 1946. He began his career in a bowling alley in 1958, and despite not pursuing higher education, this job supported him for 17 years until tax issues caused its closure.
A Journey Through Careers
After the bowling alley's closure, Rich supported his family of four sons with his wife, who dedicated 41 years to teaching in the Santa Rosa City Schools. Rich's next career spanned 27 years as a scale technician—a role he secured and excelled in with self-taught mechanical skills.
Though asked to return after retiring in 2002, Rich chose to devote his time to other pursuits rather than part-time work.
Active and Leisurely Retirement
Bowling thrice weekly and maintaining an active lifestyle have been staples for Rich. His passion extended to teaching soccer, a sport he has passionate ties with, holding a national coaching license.
He also continues to share his love of chess, a game he began in 1952, now teaching it free of charge at local libraries, passing on this legacy to his children.
Determined to keep learning, Rich participates in varied classes for seniors, enriching his retirement with educational pursuits, including courses in HTML, guitar, writing, and film.
A significant chapter in his life was concluding at home, with Rich by his wife's side during her final moments.
Living with Simplicity and Prudence
Decades ago, he bought his home for $18,200 and remains rooted in the neighborhood, valuing the stability against a backdrop of transient residency.
Rejecting common beliefs about the necessity of large savings for retirement, Rich attributes his financial comfort to frugality and pragmatism, though he didn't fund his children's college education, allowing them financial independence.
Financial Management and Legacy Planning
Unaware of the financial tools available to him initially—such as an IRA—Rich eventually allocated 15% of his income into his account, adding to his wealth even during turbulent economic times.
He plans to pass on his wealth via a structured trust, benefiting his grandchildren, ensuring they receive their inheritance with minimal conflict.
Though unsure of how to fully utilize his wealth, he finds himself comfortably positioned without depleting his savings, instead choosing to distribute gifts to his family.
Leave a Reply